Mini packet · PROP-1042-SEAPORT · FY26 Q2 close
Close / ops packet — PROP-1042-SEAPORT
Readable document for deep-page arrival from the ORG-01 seam. Same property ID. Three SAMPLE capital states. CFO checklist below — print-friendly, not a banner-only teaser.
CFO close checklist (sample · 5 lines)
- Confirm property ID on close packet matches ongoing asset record:
PROP-1042-SEAPORT(no second record). - Reconcile capital states: modeled $48.2M → committed $41.0M → funded $36.5M.
- Ledger (Yardi / MRI / equivalent) remains system of record; Fuller reconciles — does not replace the books.
- Named handoff owner Jordan Hale (Asset Manager) signs asset activation on the same ID.
- Attach closing evidence to the canonical property; deal history must survive into operations.
Buyer and triggering problem
Buyer: CFO / head of finance — the person who must match capital amount, cost, and availability to economic uses and timing.
Trigger: the firm cannot distinguish committed capital from available cash as project needs, lender conditions, and investor obligations change. A commitment gets treated as cash. Waterfalls disagree. Maturity dates live in inboxes.
Primary archetypes: investment manager / fund sponsor (ORG-02) and integrated owner/operator (ORG-01). A lender collaboration view is a restricted external case — not an automatic claim that FUND replaces lender servicing.
Bounded workflow
FUND is capital commitments and funding status — source-side capital control. It does not own project budgets or replace the designated general ledger.
Inputs
- Approved property and project uses, cash flows, timelines
- Loan proposals, executed agreements, funding conditions
- LP/GP commitments, contribution history, allocation terms
- BIT or designated ledger actuals and reconciliations
Decisions
- Select financing scenarios to recommend
- Evaluate debt terms, call timing, refinance paths
- Approve capital actions only within delegated authority
- Escalate funding gaps to leadership
Roles
- CFO owns financing strategy and liquidity visibility
- Capital markets / treasury specialists run procurement and events
- IR manages permissioned LP communication
- Controller reconciles actual receipts and payments
Outputs
- Capital stack with explicit status and timing
- Funding-gap and liquidity forecasts with evidence
- Call, distribution, and lender packages for authorization
- Capital readiness signals for transactions, projects, and BO
Status language that matters: modeled → offered → committed → closed → funded. Mixing those states is how firms invent cash they do not have.
Annotated evidence
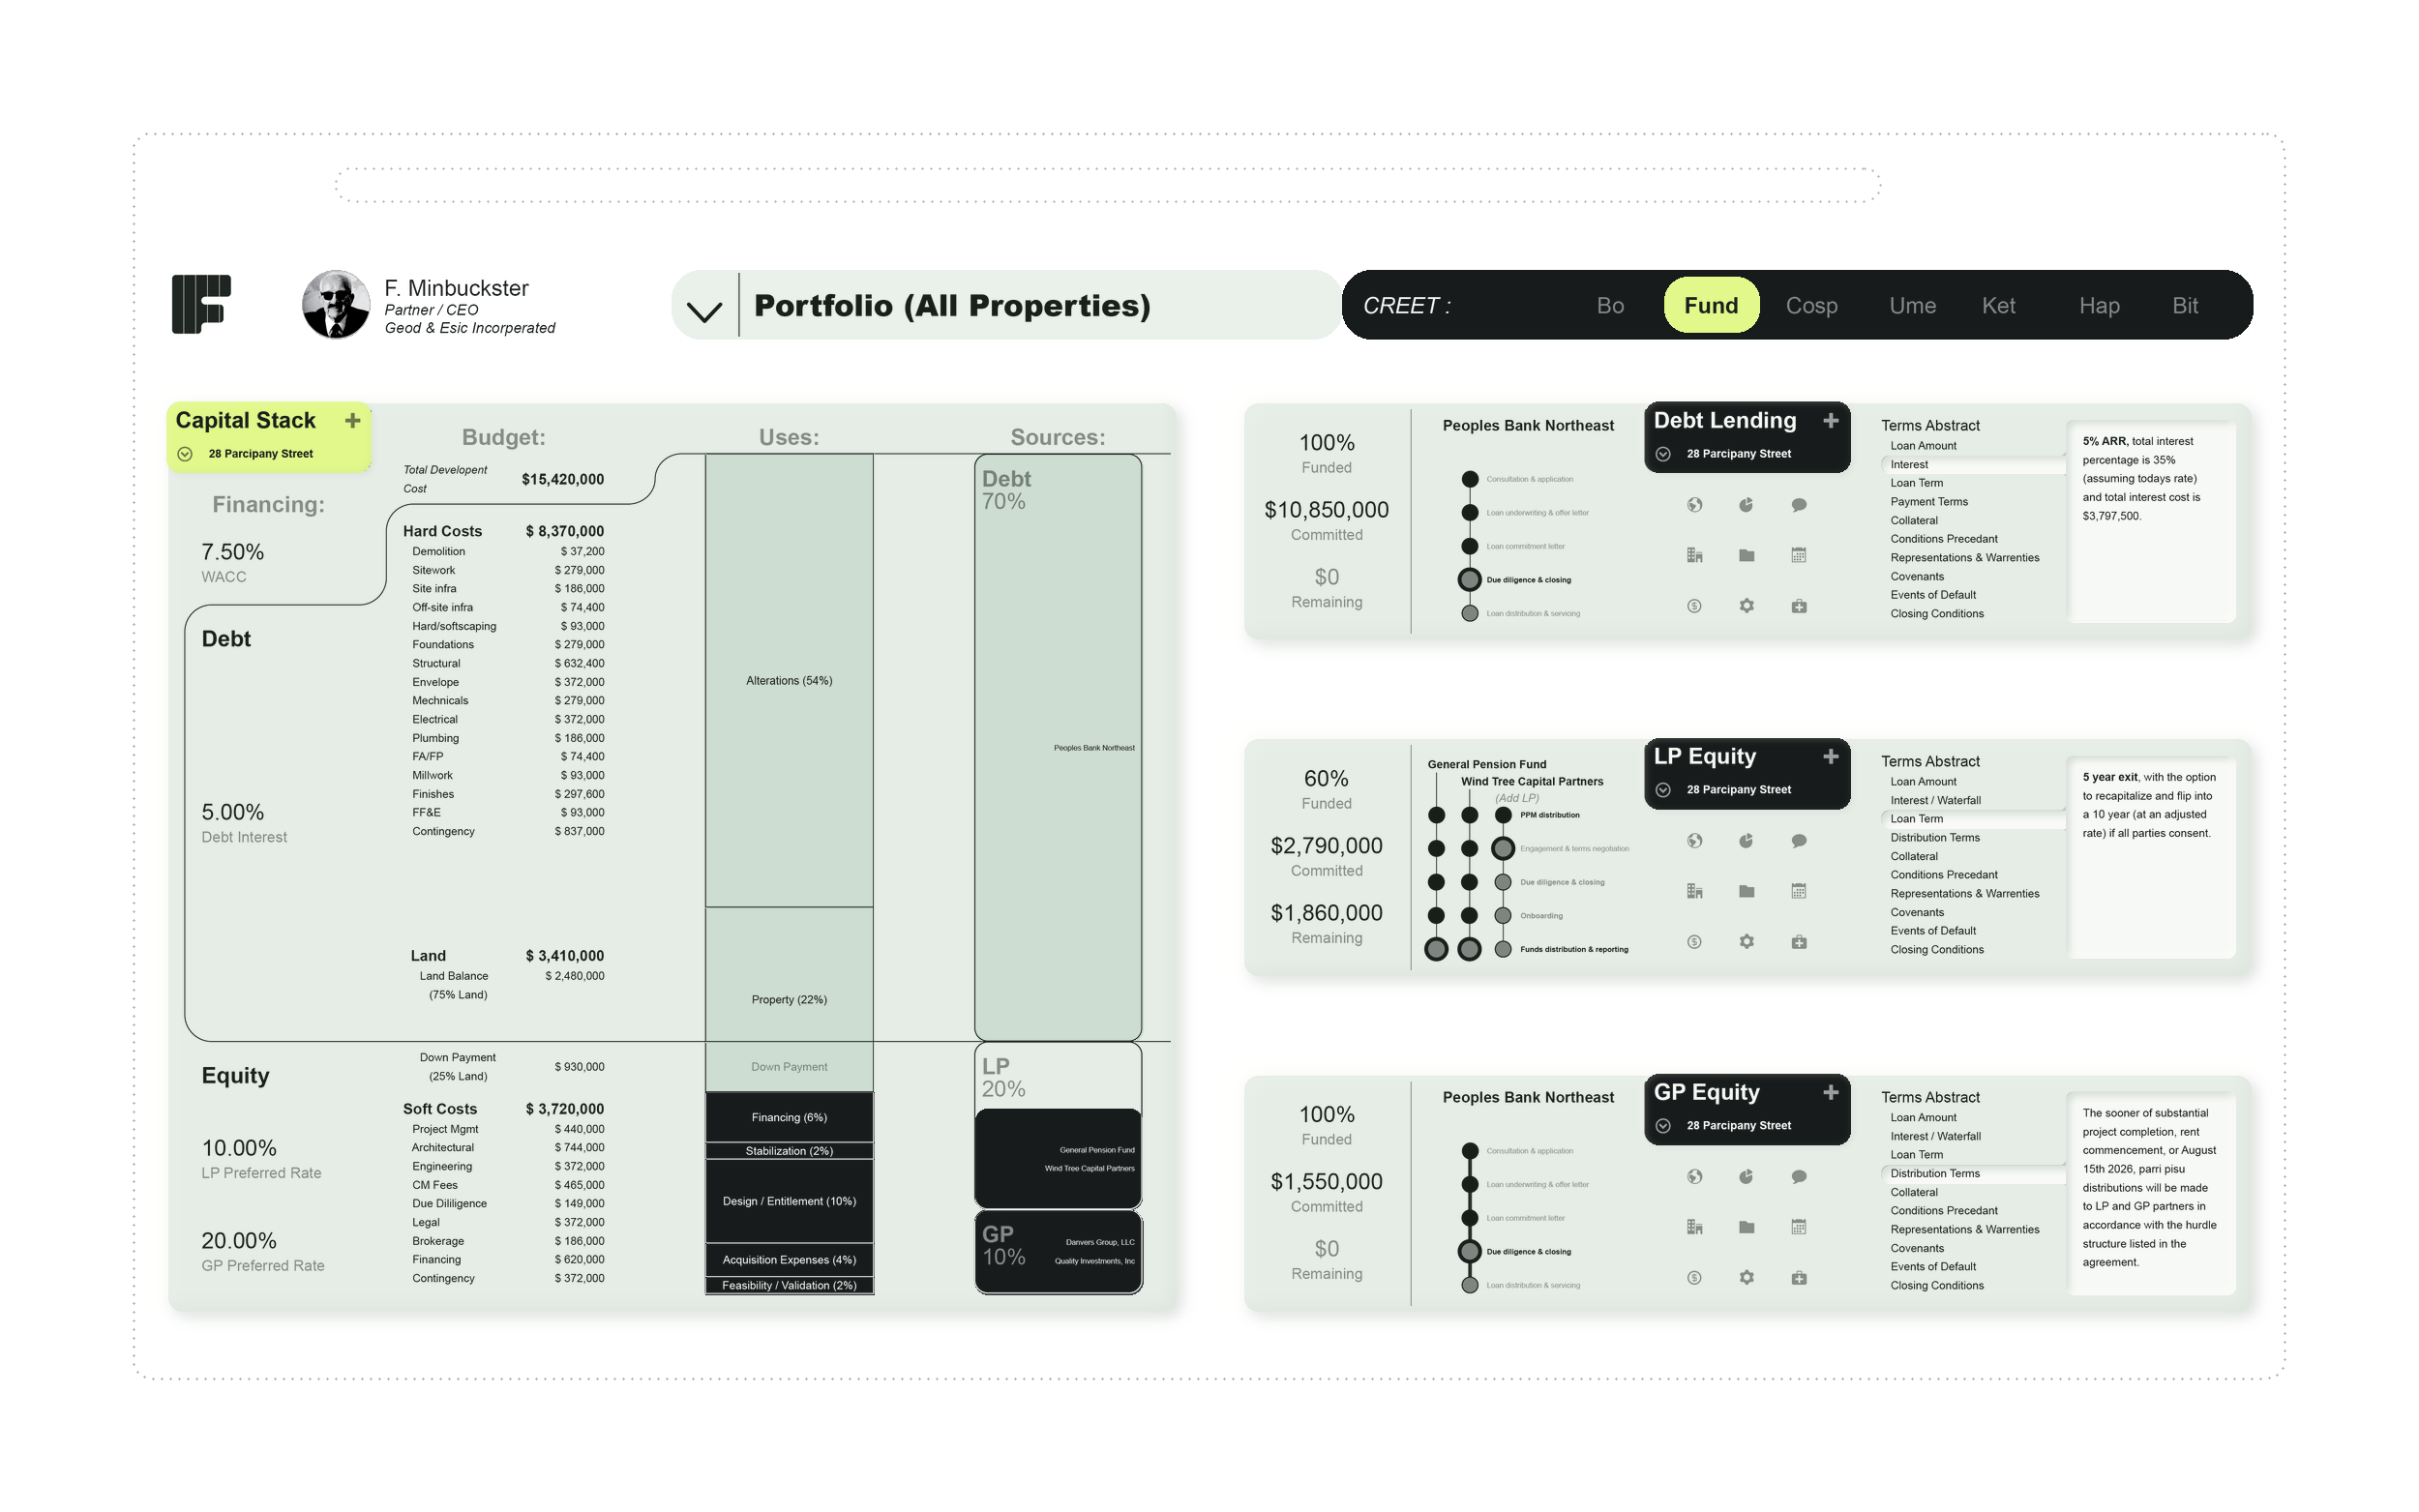
Browse FUND desk on the front door ↗ · PROP-1042 asset record ↗
Handoffs and what stays authoritative
- UME: operating cash-flow uses and assumptions in; capital cost, funding status, and obligations out.
- Framework / PROMA: budget uses and draw timing in; financing conditions and source availability out.
- COSP: closing funds and debt payoff readiness for transactions.
- BIT / ledger: actual receipts, payments, and coding — FUND models are not bank instructions.
Objections that decide the purchase
Must this reconcile with fund admin and accounting?
Yes. Require a reproducible reconciliation path and name only verified integrations. A model is not a posted transaction.
Will waterfalls match our negotiated terms?
Evaluation criterion: show calculation methods, a reproducible sample, and clear distinction between modeled events and authorized actuals.
How are investor and banking details protected?
Sponsor, lender, and individual investor information need separated permissions. Collaboration with an LP is not automatic access to the operating user model.
Availability honesty
CONCEPT INTEREST LIST NOT GA
Illustrative published list rates for CREET include capital desks at $0.01 / managed sqft / mo (label: ILLUSTRATIVE). Founding interest uses the list-vs-founding rate table on the studio door. This is not a live quote and not an account.
Join the founding MVP interest list.
This is not an account and not general availability. Tell us the workflow you need to evaluate. Founding framing includes badge + illustrative founding rates shown beside list rates at the studio door.
Join founding list ↗ Email Arthur